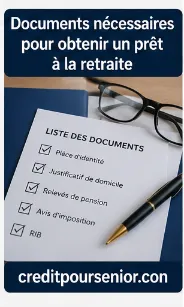
For a loan, a retiree in France usually provides five documents: an identity document, recent proof of address, payment statements from each pension, the latest tax notice and a RIB (relevé d'identité bancaire, the French bank details slip). Depending on the credit requested, the lender will add bank statements, quotes, a health questionnaire or property documents.
The Consumer Code requires lenders to check a borrower's ability to repay before granting any credit. Above 3,000 euros, the fiche de dialogue, the form listing your income and outgoings, must be backed by proof of identity, address and income. For a retiree, the hard part is not proving income but gathering statements from every fund that pays you. That task is heavier still for anyone who also draws a UK State Pension, a US Social Security benefit or an Irish occupational pension.
The basic set every retiree should prepare
Your identity document must be valid: a national identity card, a passport or a residence permit (titre de séjour). A card that expired years ago often blocks electronic signature. Proof of address, such as an energy bill, rent receipt or property tax notice, must be under three months old for some lenders and under six months for others.
The RIB must match the account into which your pensions are paid and from which instalments will be taken. Lenders check that account holder, address and identity are consistent. If you live with a relative, they will ask for a certificate of accommodation (attestation d'hébergement), the host's identity document and the host's own proof of address.
Proving how much pension you receive
The payslip is replaced by the payment statement (attestation de paiement) from each scheme: basic pension, Agirc-Arrco supplementary pension, Ircantec or a civil service scheme, plus any survivor's pension. Each can be downloaded from the fund's personal online area or, for an overview, from the joint online service shared by all French schemes. The lender adds up the net amounts. For a foreign pension, bring the annual award letter and bank statements showing the money arriving.
Why the tax notice carries so much weight
The avis d'imposition confirms the annual pension declared and reveals other income: rents, investment income, maintenance paid or received. Lenders ask for it even from retirees who pay no tax, because it shows the reference tax income (revenu fiscal de référence). Download the latest one from your online tax account. Newcomers to France who have not yet filed a French return should expect to show their last foreign tax return instead.
Paulette, 69, with three pension funds
Paulette worked in the private sector and then as a public hospital employee. She receives 980 euros from the CNAV, 410 euros from Agirc-Arrco and 520 euros from the CNRACL, 1,910 euros net in total. For an 8,000-euro loan over 48 months she supplies all three statements and her tax notice; the file is approved in four days, compared with three weeks on an earlier, incomplete application.
Full list by type of credit
Requirements vary with the nature and size of the loan. The table sums up what a retiree should prepare and where to get it.
| Document | Credit concerned | Where to obtain it |
|---|---|---|
| Valid identity document | All | Town hall or prefecture if renewal is needed |
| Recent proof of address | All | Energy supplier, landlord, property tax notice |
| Pension payment statements | All | Each fund's personal online area |
| Latest tax notice | Loans above 3,000 euros, mortgages | Your online tax account |
| Last three months' bank statements | Mortgage, leasing, debt consolidation | Online banking |
| Quote or order form | Tied loan, works, car | Tradesperson, dealer, tour operator |
| Health questionnaire | Loans with borrower insurance | Chosen insurer |
| Title deed, property valuation | Mortgage-backed loan, lifetime mortgage | Notaire, estate agent |
What a mortgage application adds
The bank also wants the preliminary sale agreement (compromis de vente), savings statements proving the deposit, repayment schedules for existing loans and, where relevant, the divorce judgment or survivor's pension award. Retirees who let out a property provide their rental income return and current leases, since rents are included in the debt ratio.
The borrower insurance file
For insurance, have ready the standard information sheet (fiche standardisée d'information) supplied by the bank, the health questionnaire and, above certain amounts, medical test results. After 60, the Lemoine law no longer exempts you from the questionnaire. Fill it in yourself, without help from the person selling the loan, and keep a copy of your answers.
Guardianship, curatorship and bereavement
A person under curatelle encloses the court order and has their curator sign alongside them; under tutelle, approval from the judge or the family council is required. A recently widowed retiree supplies the death certificate and the survivor's pension award, or failing that the receipt for the claim, to evidence future income.
Putting the file together in six steps
A complete file on first submission speeds up the answer and avoids refusals for missing documents.
- Download payment statements from every pension fund, basic and supplementary, French and foreign.
- Retrieve your latest tax notice from your online tax account.
- Check that your identity document is valid and that your proof of address is recent enough.
- Prepare a RIB for the account that receives your pensions.
- Add the project documents: quote, order form, sale agreement or valuation.
- Scan everything as legible PDFs and name each file clearly before sending.
Why a complete file can still be turned down
Documents sometimes reveal what the form left out: an undeclared revolving credit visible on the statements, rejected direct debits or a permanent overdraft. The lender also checks the FICP, the Banque de France register of loan repayment incidents. A mismatch between the pensions declared and the sums actually received raises suspicion of error or fraud, and that alone can stop the offer.
Common slips in retirees' files
Forgetting a supplementary fund lowers the income taken into account. Sending last year's statement when pensions have since been uprated creates discrepancies. Blurred photos or missing pages delay the process. And declaring gross rather than net amounts distorts the calculation of what you have left to live on.
Guarding against document fraud
Never send your papers to a so-called lender contacted through social media or a messaging app. Fraudsters use these documents to open accounts or take out loans in your name. Before sending anything, check that the institution appears on REGAFI, the official register kept by the ACPR (the French banking supervisor), and never pay fees before the funds arrive.
Alternatives when a document is missing
Some lenders offer a secure connection to your online bank, which replaces sending statements: analysing the transactions confirms your pension amounts. If you are waiting for a survivor's pension, a short bridging loan or one-off social help from your fund can fill the gap. A pawn loan from the Crédit municipal requires no proof of income at all.
Paperwork questions retirees ask
Is my original pension award letter enough? It states the amount at the time you retired, not today's figure. Lenders prefer a recent payment statement or your last three bank statements.
Do I need proof of income for a 1,500-euro loan? Below 3,000 euros the law does not require income documents, but most lenders ask for them anyway.
Can I email my documents? Yes, preferably through the lender's secure area. Avoid sending attachments to any address that is not clearly official.
Can my children prepare the file for me? They can help, but the signature must be yours unless a power of attorney or protection order authorises them.
Do foreign documents need translating? Many French lenders accept English-language pension letters, but some ask for a sworn translation (traduction assermentée). Ask before you apply to avoid delays.
Organisations and offers to contact
- Franfinance : Consumer lender listing the documents required for a home improvement loan: identity, recent proof of address, proof of income, RIB and quotes or invoices.
- Cetelem : Specialist lender whose FAQ sets out the supporting documents required, including the accommodation certificate for borrowers housed by a relative.